Table of Contents
- 1. Analyze Comparable Properties in Your Neighborhood
- 2. Review Recent Rental Listings and Market Trends
- 3. Factor in Property Features and Condition
- 4. Consider Location Desirability and Proximity to Amenities
- 5. Evaluate Tenant Demand and Seasonal Fluctuations
- 6. Use Our Free Rental Market Analysis Tool
- 7. Account for Orange County Economic Indicators
- 8. Monitor Supply and Demand Dynamics in Your Area
- Frequently Asked Questions (FAQ)
1. Analyze Comparable Properties in Your Neighborhood
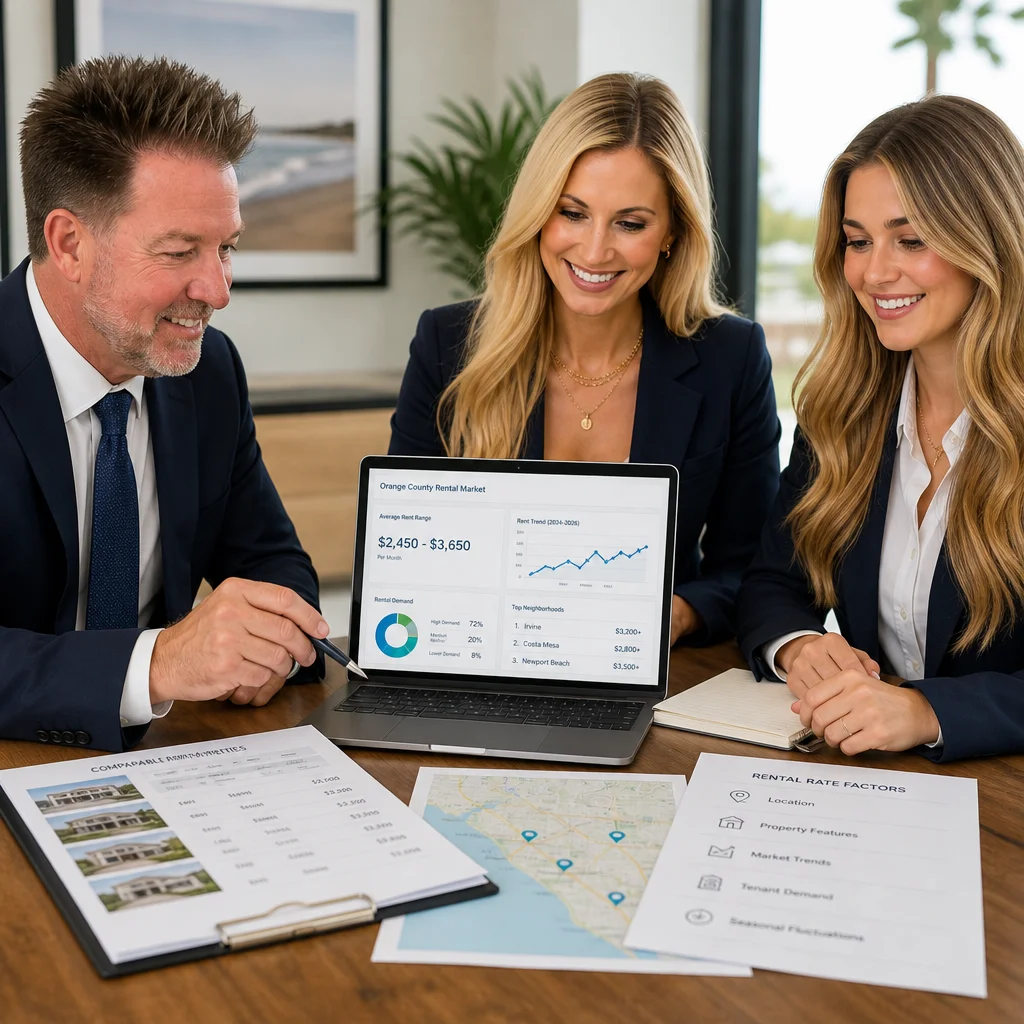
Start by looking at what similar properties are renting for in your immediate area. This is the foundation of any solid rent estimate. “Comps” give you real proof of what the market will bear, rather than relying on guesses.
Focus on properties that match yours as closely as possible: same number of bedrooms and bathrooms, similar age, comparable square footage, and ideally within a three-block radius or the same neighborhood cluster. If you’re renting a three-bedroom, two-bath home built in 2005, don’t compare it to a four-bedroom mansion or a studio apartment. The details matter because tenants are comparing these exact features when they’re house hunting.
Look at properties that have actually rented or sold recently, not those that have been sitting on the market. A listing that’s been stale for six months signals either overpricing or serious issues, and either way, it’s not reliable data for your estimate.
What to do next: Search your neighborhood on major rental platforms and note the asking prices for true comparables. Create a simple spreadsheet with five to ten properties and their rent amounts. The middle values give you your realistic range.
2. Review Recent Rental Listings and Market Trends
Active rental listings tell you what landlords are asking for right now, but you also need to understand whether those asking prices are actually what tenants are paying. There’s often a gap between what landlords list and what deals actually close.
Orange County’s rental market shifts throughout the year. Spring and summer typically see higher rental rates and more competition among landlords, while fall and winter can soften demand slightly. If you’re setting rates in January, you might price more competitively than you would in May. Tenants moving for jobs or school year transitions create predictable seasonal patterns you can leverage.
Look at listing trends over the past 60 to 90 days rather than just today’s snapshot. Are prices trending upward or downward in your specific neighborhood? A neighborhood where rents are climbing tells you it’s safer to price on the higher end of your range. A declining trend suggests you should be more conservative.
What to do next: Check rental sites weekly for 30 days and track the asking prices you see. Note whether properties are getting rented quickly (a sign of competitive pricing) or sitting vacant for weeks (a sign of possible overpricing).
3. Factor in Property Features and Condition
Two homes with identical square footage can command very different rents based on their condition and amenities. A freshly renovated kitchen, updated flooring, modern appliances, and good natural light justify premium rates. A property that needs repairs or has outdated fixtures will rent for less, even if the bones are solid.
Be honest about your property’s condition. Recent upgrades like new HVAC systems, energy-efficient windows, or recent roof work are genuine selling points that tenants notice and will pay more for. On the flip side, deferred maintenance like aging plumbing, worn carpeting, or failing appliances will reduce your achievable rent range significantly.
Amenities matter too. A garage, yard space, laundry hookups, or a deck add value. Pet-friendly policies, covered parking, or access to shared community amenities are features tenants actively seek. Properties with these features consistently rent at higher rates in Orange County’s competitive market.
What to do next: Walk through your property like a prospective tenant would. Note which features are above average, average, and below average compared to your comps. Adjust your rent estimate up or down based on this honest assessment.
4. Consider Location Desirability and Proximity to Amenities
Not all Orange County neighborhoods carry equal rental weight. Location desirability directly impacts what tenants will pay. Proximity to job centers, public transportation, shopping, dining, parks, and good schools all influence rental rates.
A property two blocks from a Metrolink station or near a major employment hub commands higher rent than an identical property in a more isolated area. Similarly, homes near top-rated school districts attract families willing to pay premium rates, even if those families don’t have children currently. Good schools signal neighborhood quality and long-term appreciation.
Walk scores matter too. If your property is in a walkable area with convenient access to grocery stores, restaurants, and entertainment, tenants will recognize that value. Properties in car-dependent areas need stronger pricing incentives to attract interest.
What to do next: List the five to seven closest amenities to your property and note their distance. Compare this to your comparable properties. If your location is noticeably more convenient, you can justify a higher rent. If it’s less convenient, adjust downward.
5. Evaluate Tenant Demand and Seasonal Fluctuations
Tenant demand varies by season, neighborhood, and even by day of the week. Understanding demand patterns helps you time your listing and set realistic rates.
Late spring through early fall sees peak tenant demand. Families want to move before the school year starts, and young professionals are transitioning jobs. This high-demand period lets you charge at the higher end of your range because you’ll have multiple qualified applicants competing. In October through February, demand softens, which means you’ll need more competitive pricing to attract quality tenants quickly.
Supply in your specific neighborhood also affects demand. If five similar properties are listed in your area at the same time, you’re in a competitive situation and need to price smartly. If you’re the only property available, you have leverage to price higher.
What to do next: Check how many similar properties are currently listed in your neighborhood. If it’s low (fewer than three), you can price toward the top of your range. If it’s high (more than five), be more competitive. Pair this with the current season to finalize your estimate.
6. Use Our Free Rental Market Analysis Tool
We offer a free rental market analysis tool specifically designed for Orange County landlords. This isn’t just a quick calculator; it’s a detailed market report that factors in the neighborhood-specific data most landlords miss.
Our tool pulls together comparable property data, current market conditions, tenant demand patterns, and economic indicators specific to your address and Orange County submarket. You’ll get a rent range recommendation backed by real data, not just industry averages. The report shows you exactly how your property stacks up against current listings and what you can reasonably expect to achieve.
Many landlords guess or rely on outdated information, which costs them money. Our analysis gives you confidence because you’re working with current, location-specific data. You’ll see which features add value in your specific neighborhood and where your property falls in the local rent spectrum.
What to do next: Run your property through our rental market analysis tool. It takes just a few minutes and gives you a detailed breakdown of your property’s rental value based on today’s Orange County market conditions.
7. Account for Orange County Economic Indicators
Broader economic trends affect what tenants can afford and what they’ll prioritize. Job growth in Orange County generally supports higher rental rates because employment stability means higher tenant income and lower turnover risk.
Interest rate environments matter too. When mortgage rates are high, more potential homebuyers stay in the rental market longer, increasing demand and supporting higher rents. When rates drop, some renters transition to homeownership, reducing demand slightly.
Wage growth in your area signals tenant purchasing power. If major employers in Orange County are hiring aggressively or expanding, rental demand typically strengthens. Local cost of living trends also influence what percentage of income tenants can dedicate to rent.
What to do next: Check recent Orange County employment reports and wage growth statistics. If economic indicators are strong (job growth, wage increases, low unemployment), you can price more confidently toward your upper range. If economic conditions are softer, be more conservative.
8. Monitor Supply and Demand Dynamics in Your Area
The relationship between available rental properties (supply) and prospective tenants (demand) determines pricing power. When demand is high and supply is low, you can price aggressively. When supply is high and demand is soft, you need to be competitive.
Track active listings in your neighborhood monthly. A shrinking number of available rentals signals tightening supply and supports higher rates. Growing inventory suggests you’ll need more competitive pricing to attract tenants quickly.
Tenant inquiries and showing activity give you real-time feedback on your pricing. If you list a property and get five qualified applications in the first week, you likely priced slightly low and could have charged more. If weeks pass with minimal interest, you’re probably priced above market.
Your rental market analysis should be dynamic, not static. Check your comps and market conditions quarterly. Orange County’s market moves fast, and what was accurate three months ago might need adjustment now.
What to do next: Set a calendar reminder to reassess your rental rate every three months. Pull fresh comparable data, check current listings, and adjust your rate up or down based on new information. This keeps you competitive and maximizes your annual revenue.
—
Estimating Orange County rental rates accurately requires combining multiple data sources and staying grounded in current market conditions. You’re balancing property-specific details with neighborhood dynamics, seasonal patterns, and economic trends. That’s a lot to juggle alone, and missing even one variable can cost you thousands annually.
The smartest move is to use your own analysis combined with our free rental market analysis tool. You’ll get a comprehensive, data-backed estimate that reflects today’s Orange County market, not yesterday’s assumptions. From there, our team can help you implement your pricing strategy, screen tenants professionally, and manage your property with complete transparency on fees and returns. We handle the tenant management complexity so you can focus on maximizing your rental income. Start with our free rental market analysis today and see exactly what your property should rent for in 2026.
For further reading: Pricing your rental property, Orange County rent estimates.
Contact Us Today And Schedule Your Free Rent Review and Consultation at 949-688-7705
Frequently Asked Questions (FAQ)
How accurate is our free rental market analysis tool for Orange County properties?
We’ve built our tool to give you the most current data available in Orange County’s market. Our analysis pulls from recent listings, comparable properties in your neighborhood, and real-time demand signals to provide rental estimates tailored to your specific property. While market conditions shift seasonally, we update our data continuously so you’re working with the freshest information to set competitive rates.
What economic factors should we monitor to adjust rental rates throughout 2026?
We recommend tracking Orange County’s employment trends, interest rates, and new housing development as primary indicators. These factors directly influence tenant demand and purchasing power in your area. We also suggest reviewing unemployment rates and wage growth quarterly, since renters’ ability to afford housing shifts with local economic conditions. Our platform helps you monitor these indicators so you can adjust your pricing strategy proactively rather than reactively.
How often should we re-evaluate our rental pricing strategy?
We suggest reviewing your rental rate at least annually, though we recommend checking it quarterly if you’re in a highly competitive neighborhood. Market conditions in Orange County can shift based on seasonal demand, local job growth, and new competition. When you’re preparing for lease renewals or turnover, that’s an ideal time to reassess what comparable properties are commanding so you can maximize your returns without pricing yourself out of the market.